 DGactual
Hot Jobs, a Rate Hike on the Table, and a Used Market That Keeps Sliding | Week of November 9, 2026
Payrolls beat forecasts, Fed hike odds rose to about 78%, and DARPI logged its seventeenth straight decline. Plus October sales, the Cybertruck wind-down, and the monthly Scoreboard with a preview of our five-month ratings study.
Friday morning handed the economy a good report card and handed car buyers a bill. Employers added 165,000 jobs in October, more than three times the 48,000 monthly average of the past year, and within hours traders put the odds of a Federal Reserve rate hike next month at about 78%. A hike is the last thing a shopper financing a car wants to hear, and it lands in a used market where our price index just logged its seventeenth straight decline.
Overview
Here is the week in one breath. The jobs report came in at more than double what forecasters expected, unemployment slipped to 4.1%, and consumer sentiment rose to 51.0. October new-vehicle sales ran at a steady pace, with hybrids doing the lifting. Tesla said it will wind down the Cybertruck. DARPI, our used retail price index, fell for the seventeenth reading in a row, while our for-sale-by-owner desk shows private sellers undercutting dealers on several popular models.
We also have the monthly Dealer Reputation Scoreboard, where 92.2% of stores kept the same Google rating, plus a first look at five months of ratings data. Then a look ahead to Tuesday's inflation report, the last one the Fed sees before it meets in December.
Jobs and the Fed
The Bureau of Labor Statistics reported on Friday, November 6, that payrolls rose 165,000 in October, far above what forecasters expected. The bureau also revised September up to 60,000 from 29,000, so the recent trend is stronger than it looked a month ago.
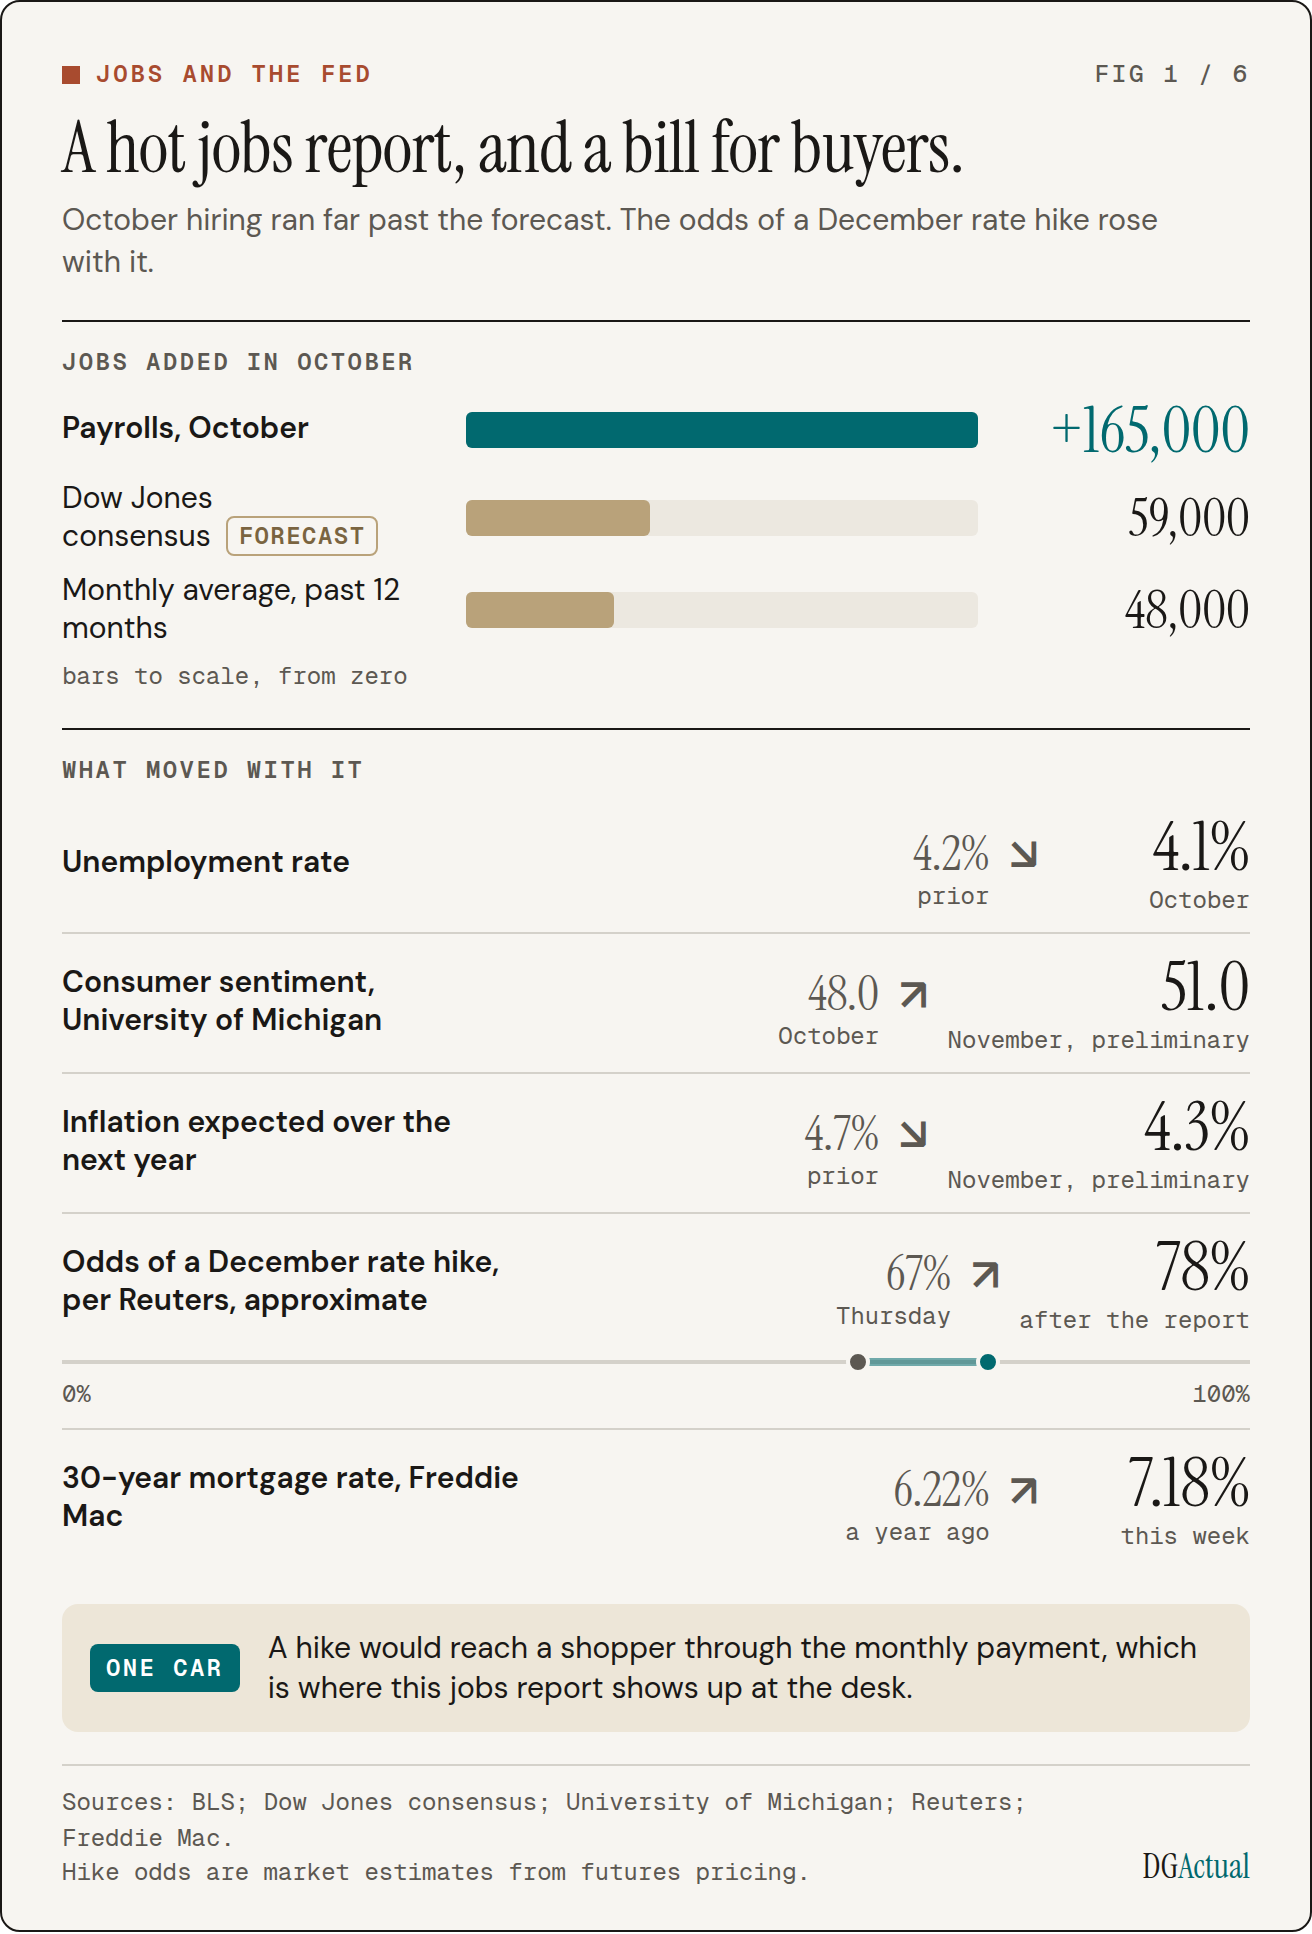
Reuters reported that the data pushed the Fed's debate toward a December hike, with markets pricing roughly a 78% chance of a quarter-point increase at the meeting on December 8 and 9. That would lift the federal funds target range one step, to 4.00% to 4.25%. Those odds come from futures pricing; the Fed itself has not said what it will do in December.
Households sound a little less gloomy than last month. The University of Michigan's preliminary November reading of consumer sentiment rose to 51.0, and people expect smaller price increases over the next year. The survey still found that a majority of respondents said high prices were eroding their living standards. Interviews ended on November 2, before the November 3 election results were known, so the final reading on November 20 will show whether the mood held.
Borrowing costs are a mixed picture. Freddie Mac's 30-year mortgage rate fell for a third straight week to 7.18%, though it still sits nearly a full point above a year ago. Gas helped a little: AAA put the national average at $4.10 a gallon on November 5, down 12 cents in a week.
October Sales
Start with our own model. It projects fourth-quarter vehicle sales at a 16.22 million annual pace, down from 16.65 million in the third quarter. About two times in three, its projections have landed within half a million of the actual. Our measure runs higher than the readings below because it also counts medium and heavy trucks, so that gap is a definition, not a disagreement. One honest caveat: so far, simply assuming next quarter matches this one has been slightly more accurate one quarter out.
New-vehicle sales held their pace. NADA put October's SAAR at 15.54 million, 0.9% below last October. SAAR is the seasonally adjusted annual rate, the number of vehicles the market would sell over a full year if that month's pace held. J.D. Power and GlobalData had forecast 15.6 million in late October, flat with a year ago, so the month landed close to expectations.
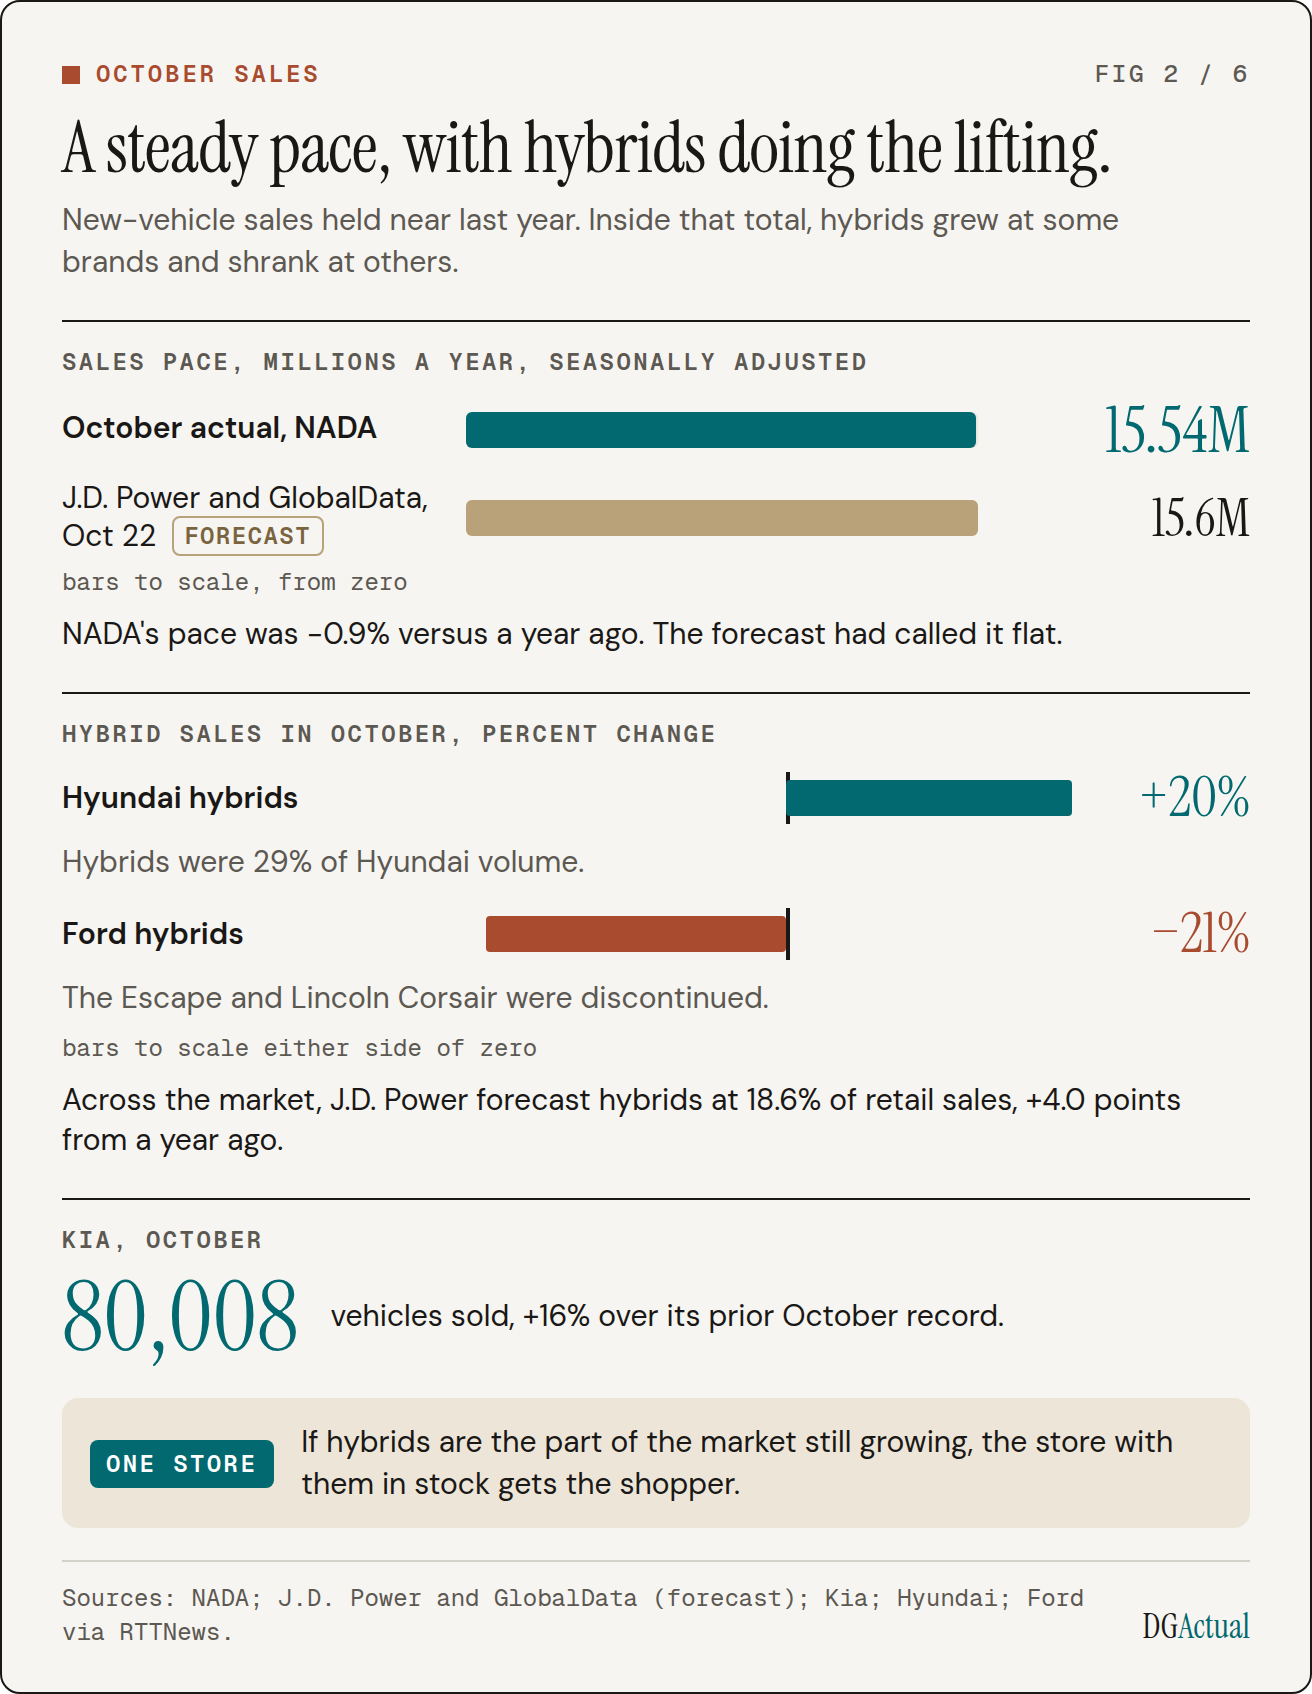
The mix is where the story lives. J.D. Power's October forecast put hybrids at 18.6% of retail sales, up 4 points from a year ago. Kia and Hyundai both set October sales records, and Hyundai's hybrids grew by a fifth. Ford went the other way, with hybrid sales down 21% as the discontinued Escape and Lincoln Corsair rolled off.
For a dealer, that is an allocation question. If hybrids are the part of the market still growing, the stores that stock them are the ones getting the lift, and Hyundai and Kia dealers in particular may want to review hybrid supply with their regional teams.
Cybertruck
Tesla CEO Elon Musk said on Friday that the company will wind down Cybertruck production at its Texas factory around the middle of next year to make room for more of its Cybercab robotaxi. Reuters noted that the Austin plant is the only known Tesla facility equipped to build the truck's specialized components, and Musk did not say what happens to outstanding orders. A day later he said Tesla is still building Cybertruck for another eight or nine months.
For a store, the useful detail came from Tesla's lead engineer on the truck, who said spare parts and service support will continue. Our read, and it is an inference, is that Cybertruck owners remain a service-drive customer for years, whatever happens to new production.
DARPI
DARPI tracks used retail asking prices from dealer listings across 11 vehicle segments, indexed to 100 at June 8. The Near-New index fell to 93.02, its seventeenth straight decline. We count readings rather than weeks, and the first decline in this run came on July 17.
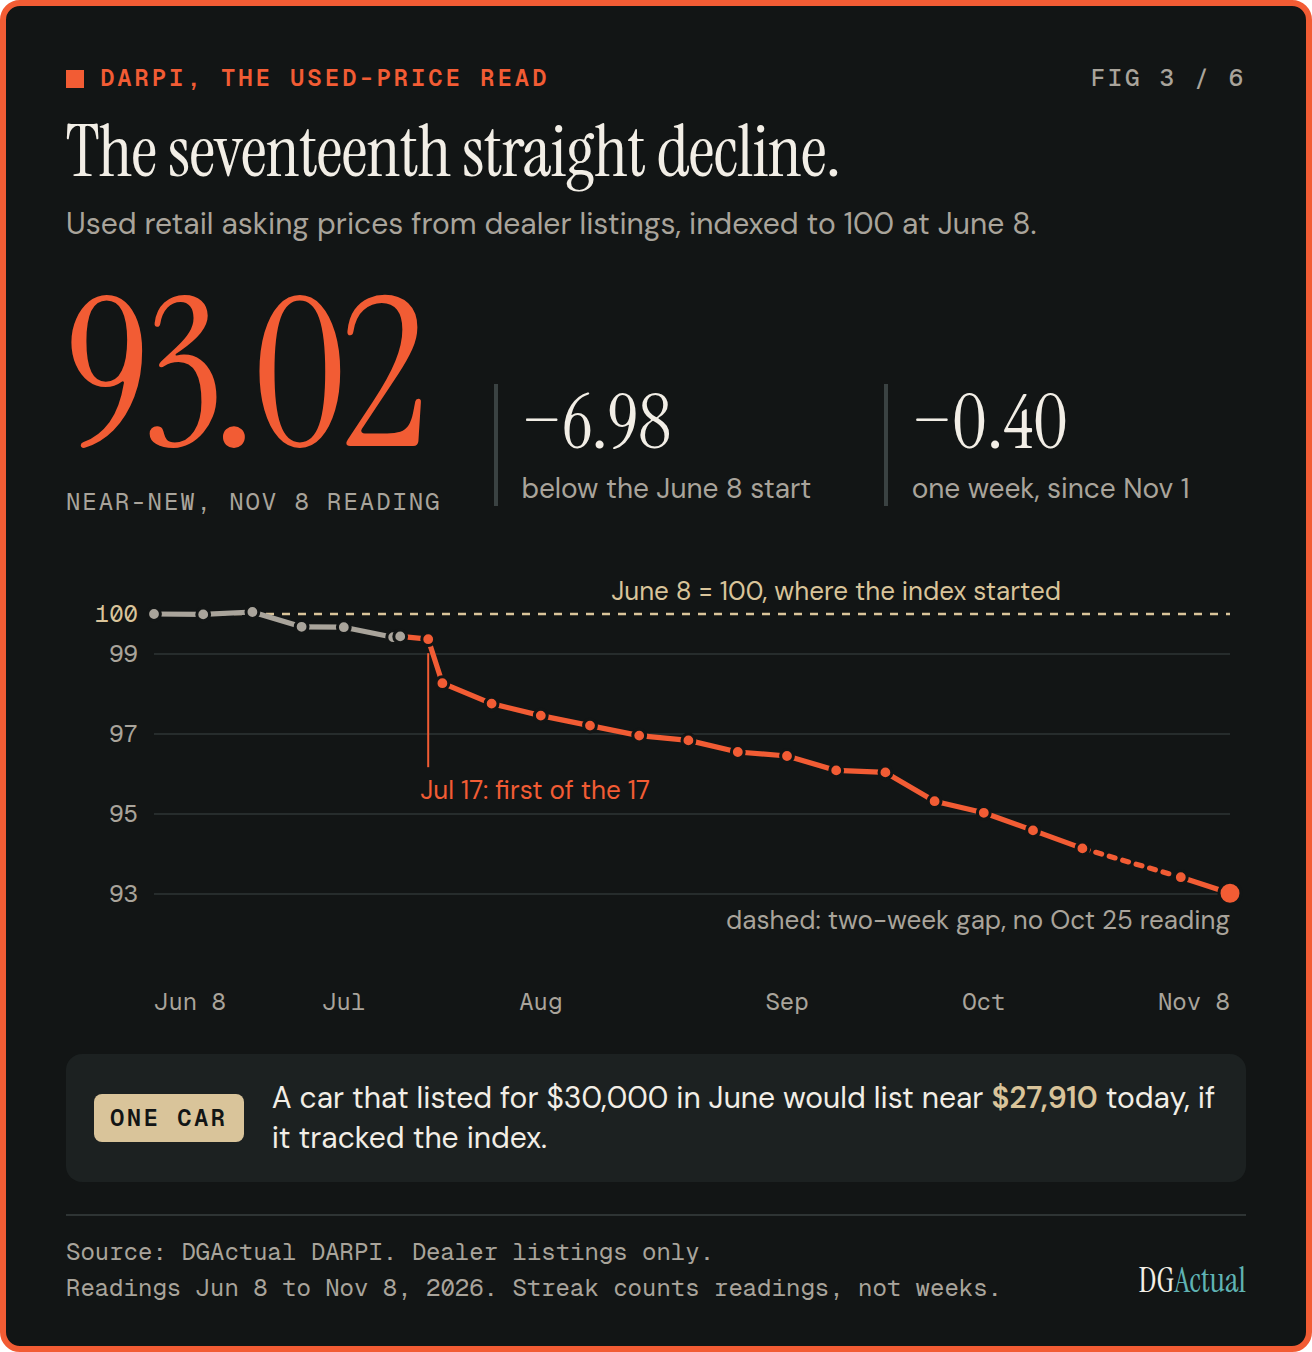
The spread between our retail read and the Manheim wholesale index widened to negative 4.11 points from negative 3.28. Both sides moved: dealer asking prices fell 0.40 points, and the wholesale index, which updates once a month, ticked up 0.43 points with its October release. Measured from June, asking prices are down 6.98 points while wholesale is down 2.87, so retail has fallen more than twice as far.
The week's biggest moves were in Midsize Car, down 0.65, and Minivan, down 0.58. Electric vehicles rose 0.54, a small bounce that leaves the segment well below where it started. One honest limit: DARPI is asking prices from one listings provider, and it does not measure what cars actually sell for.
FSBO Desk
FSBO means for sale by owner, a private seller listing directly instead of through a dealership. Every comparison below runs both sides through the same mileage band, covers model years 2022 to 2025, and shows how many matched private listings sit behind it. Matched counts are small for most models, so treat them as leads.
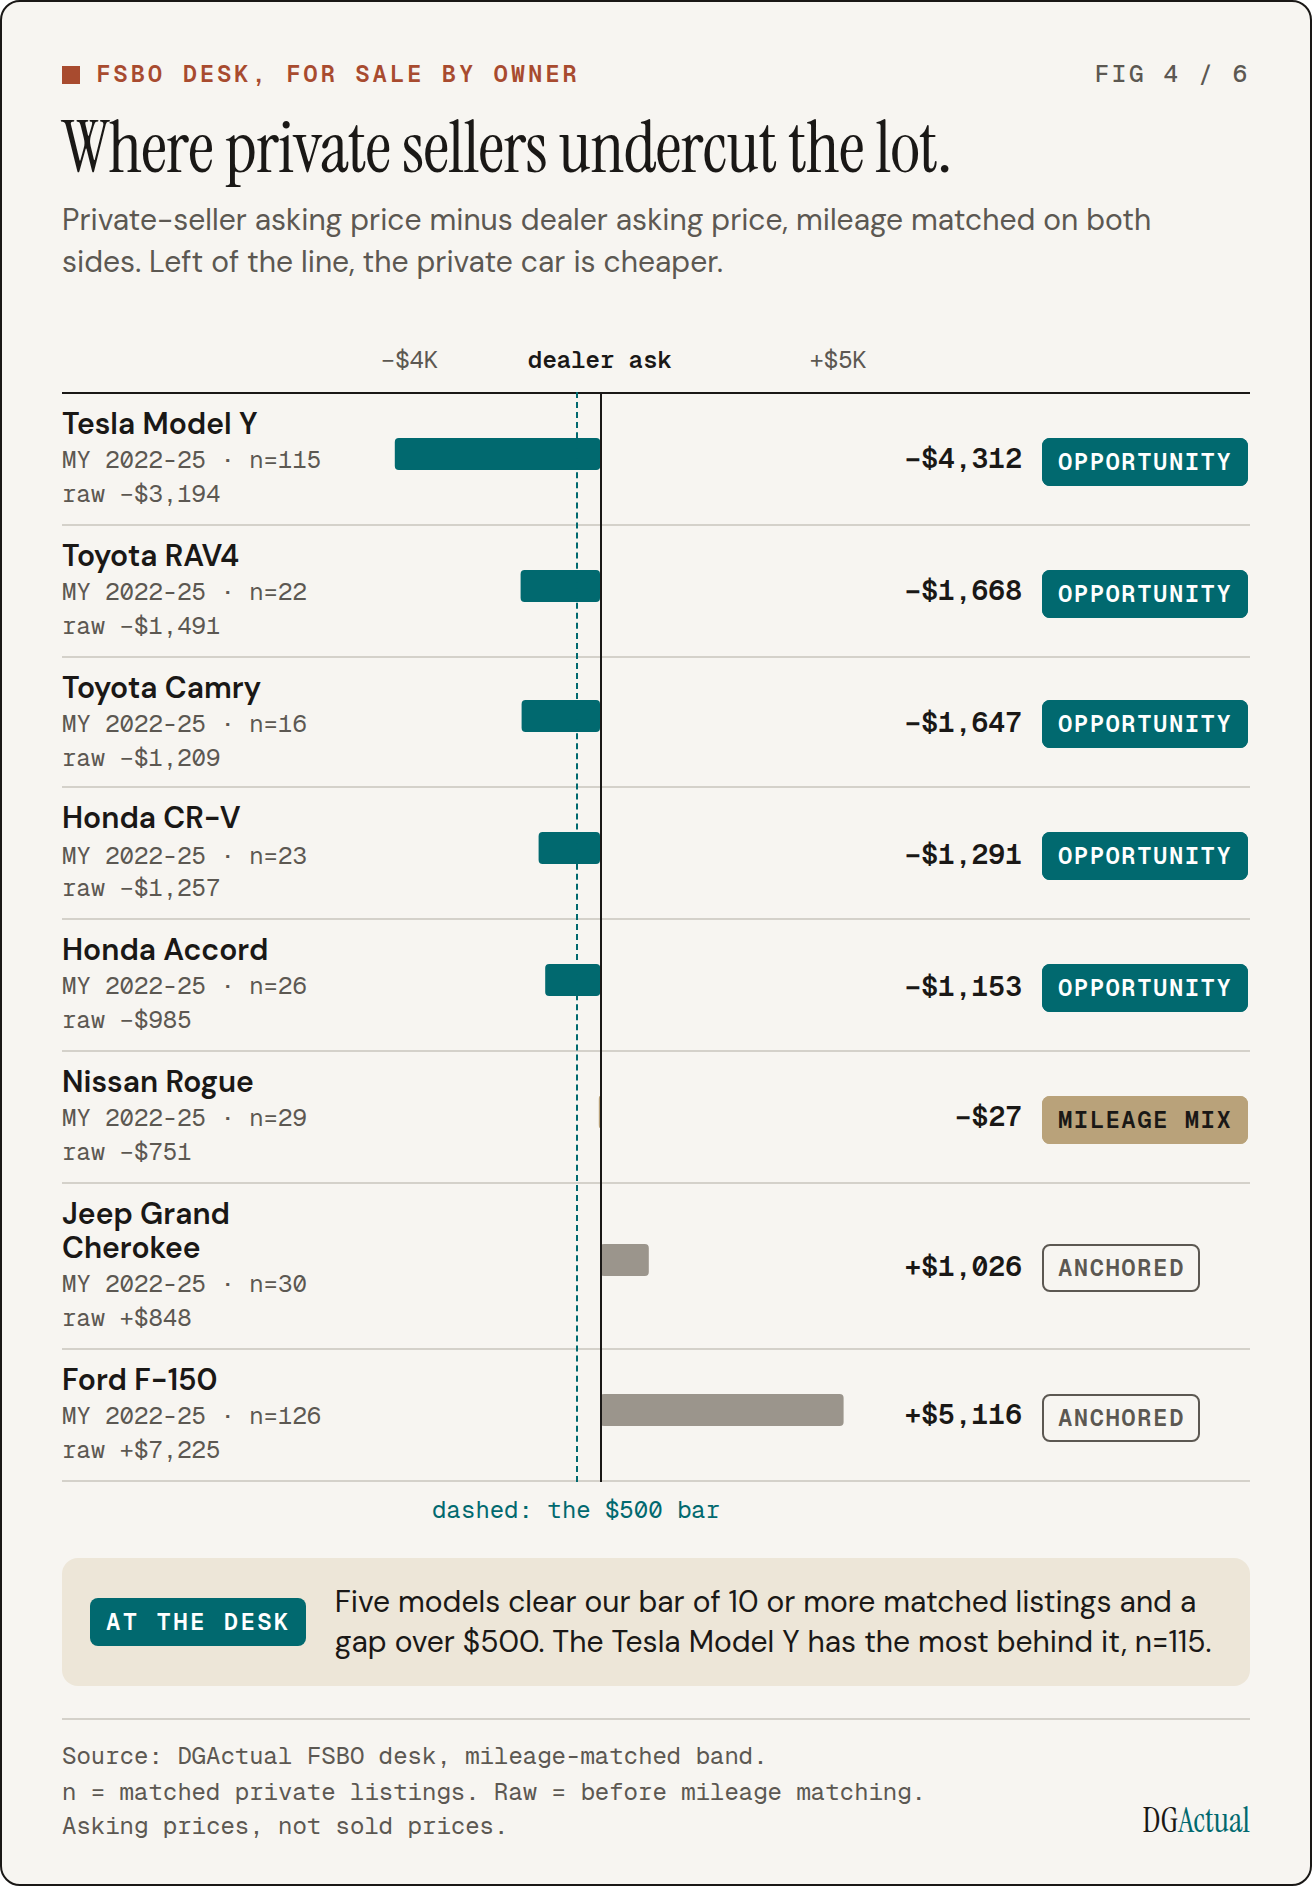
Two models have enough listings to lean on, and they point opposite ways. Private Tesla Model Y sellers are asking $4,312 below dealers on matched mileage, while private F-150 sellers are asking $5,116 above. A Model Y buyer has a real reason to shop private; an F-150 buyer mostly does not.
Several other models show private sellers cheaper, led by the RAV4 at $1,668, but with only 16 to 26 matched listings each. The RAV4 was ANCHORED last week and flipped this week, which is a reason for caution and not a trend. The Nissan Rogue looks $751 cheaper on raw numbers and only $27 once mileage is matched, a mileage mix and not a discount.
Scoreboard
The monthly Dealer Reputation Scoreboard at reviews.dgactual.com, which tracks Google ratings for franchise dealerships, finished its November refresh on Friday. To compare fairly, we keep only stores that appear in both the October and November snapshots with at least 100 reviews and review growth of no more than 25%, which leaves 12,970 of 18,065.
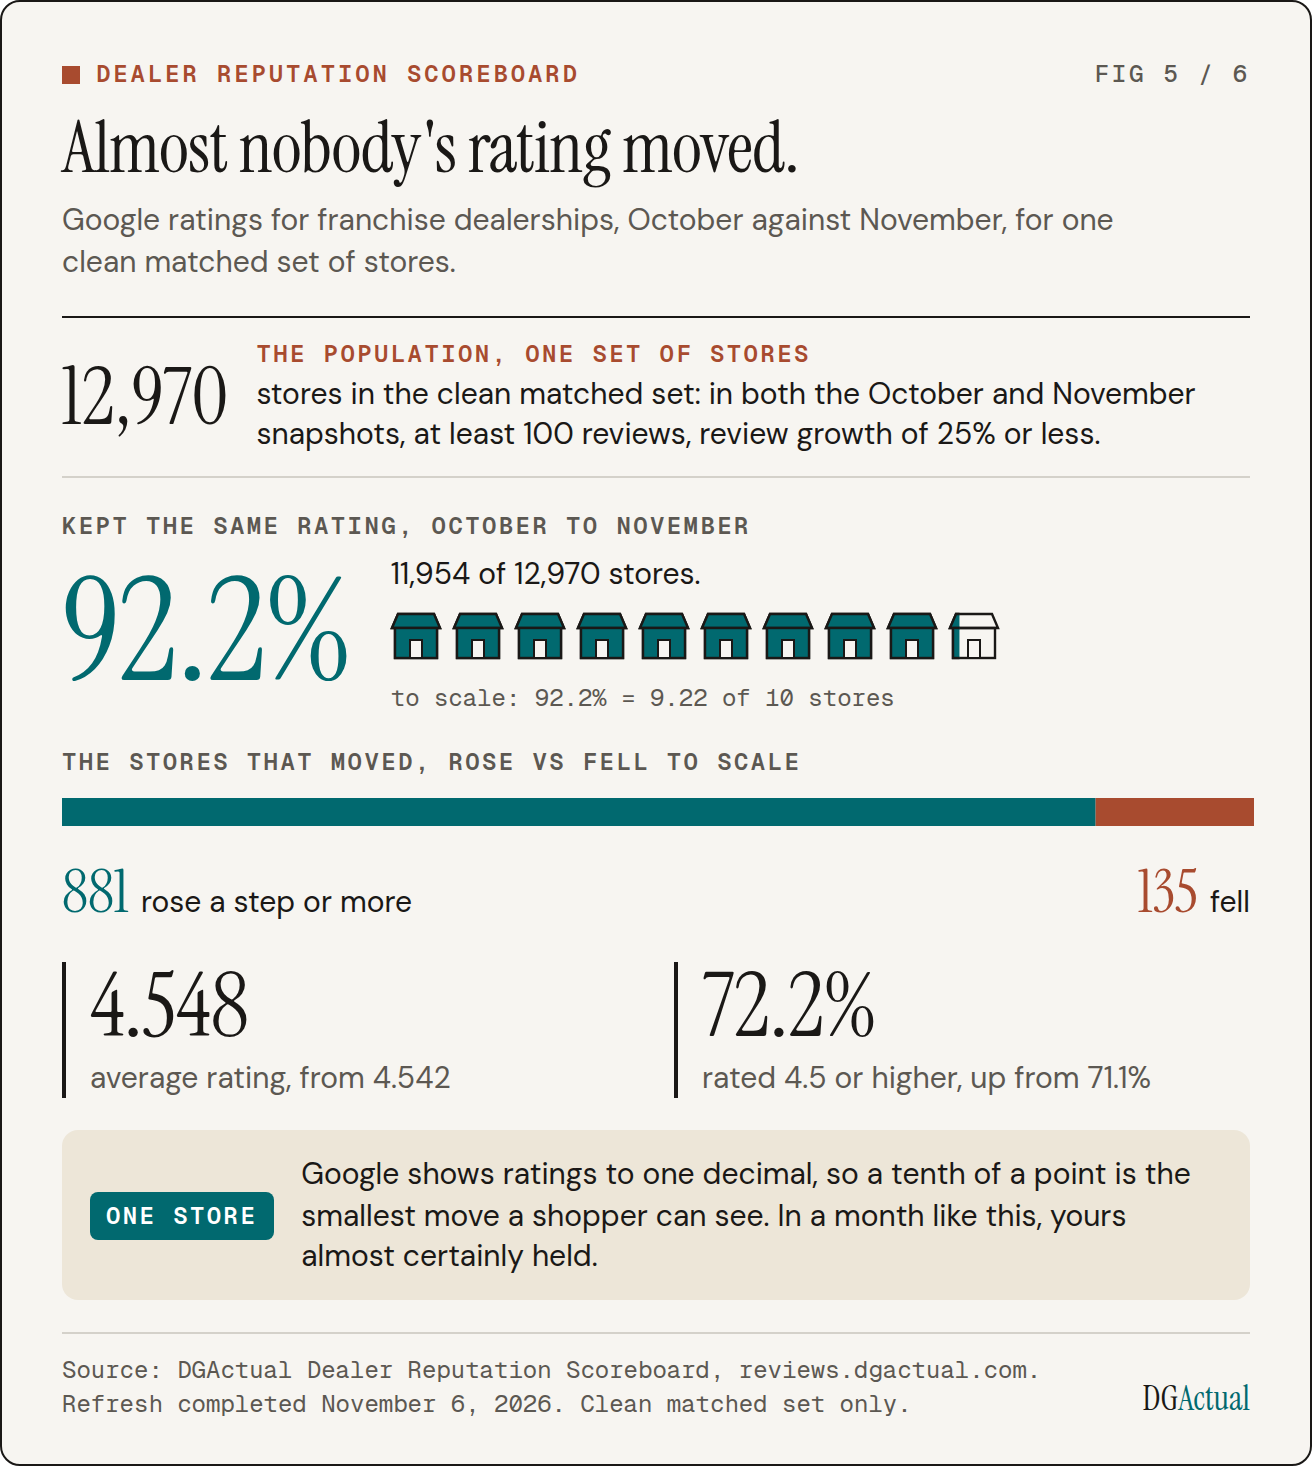
Almost nothing moved: 92.2% of those stores kept the same rating. Among the stores that did change, more than six rose for every one that fell, which nudged the share rated 4.5 or higher up by about a point. Google rounds ratings to one decimal, so a one-tenth change is the smallest step you can see, and a store sitting at 4.4 is one step from the 4.5 line.
Reviews kept arriving at a steady pace, about a percent on the existing base, with Lamborghini fastest and Ram slowest. Across the whole site, which covers 17,103 dealers, the average rating is 4.51.
A preview of something bigger. We now have five monthly snapshots, July through November, so we looked at the 17,031 stores that were rated in every one. That is a different view from the one-month comparison above, and the full write-up is coming soon. Here is a first look at what stood out.
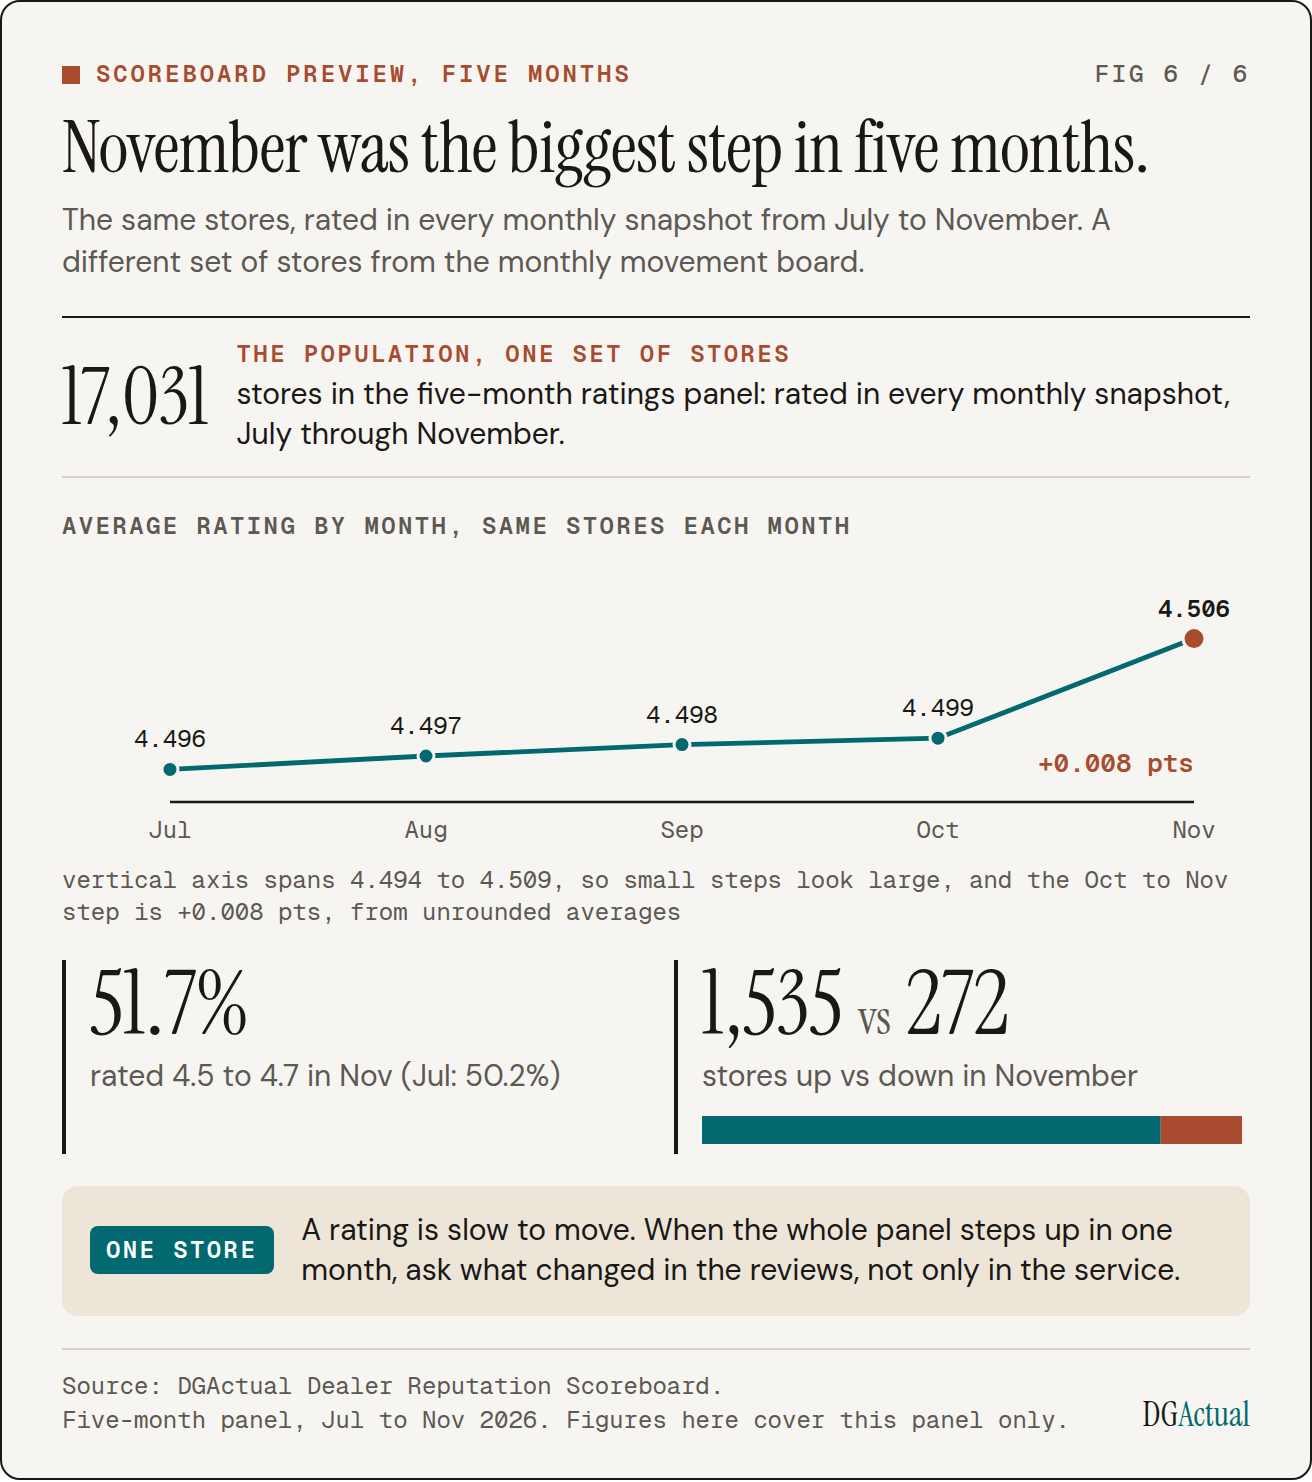
November was the biggest step of the five months, though the step itself was small. The average rating of these stores rose about eight thousandths of a point, against roughly one thousandth a month from July to October. The median store moved from 4.5 to 4.6 for the first time, and since July a net 301 stores have crossed above the 4.5 line.
Reviews did something we have not seen before in this data. In November, 15% of these stores ended the month with fewer reviews than they started with, compared with 2.5% to 3.3% in each earlier month, about 5 times the usual rate. The November snapshot was a complete refresh, so this is not a stale-data artifact, but the data cannot tell us why those reviews disappeared.
Finally, ratings are stubborn. 78% of stores never changed their rating in any of the four monthly steps. The arithmetic explains why: a store sitting at 4.50 needs roughly 11% more reviews, every one of them five stars, to reach 4.55. The full analysis adds the brand and state detail, and the questions we think are worth asking next.
Safety Desk
GM is recalling 67,380 electric vehicles over a software defect in the brake control module that can cause a loss of braking. The recall covers the 2023 to 2027 Cadillac Lyriq, the Celestiq, the Vistiq and the 2024 to 2027 Chevrolet Blazer EV. The fix is a free software update, over the air or at a dealer. If you sell or service those models, check open recalls before a car leaves the lot.
NHTSA also put $1.5 million behind a plan to help states flag open recalls when drivers register or renew a vehicle. For a store, that means more customers may learn about a recall at the registration counter instead of in your service drive.
Week Ahead
Tuesday is the day to circle. The Bureau of Labor Statistics publishes October's Consumer Price Index at 8:30 a.m. on Tuesday, November 10, the last inflation report the Fed sees before its December decision. At 11 a.m. the same day, the New York Fed releases its third-quarter Household Debt and Credit report, which includes auto loans. The Producer Price Index, which tracks what businesses pay, follows on Friday, November 13.
October retail sales land Tuesday, November 17, and the University of Michigan's final November sentiment reading follows Friday, November 20, with interviews taken after the election. The next jobs report is Friday, December 4, and the Fed meets Tuesday and Wednesday, December 8 and 9.
Update on earlier spread figures: our retail-wholesale spread compares weekly retail asking prices with a wholesale index that updates once a month. The September wholesale reading had not been added to our comparison when our October 12, October 19 and November 2 posts ran, so the spread in those posts was measured against an older wholesale value.
With the September reading included, those figures are negative 2.11, negative 2.56 and negative 3.28, in place of the negative 3.16, negative 3.61 and negative 4.33 we reported. The October wholesale reading arrived this week and is part of the negative 4.11 above. The retail figures in those posts are unchanged, and each post now carries a short note. We are always checking and refining our analysis to make it as exact as we can, and improving it as we go is part of the work.
Sources
Every outside figure above comes from the following sources. Our own figures come from DGActual DARPI, the DGActual FSBO desk, the DGActual Dealer Reputation Scoreboard and the DGActual SAAR model.
Sources: U.S. Bureau of Labor Statistics, The Employment Situation, October 2026 (November 6, 2026); U.S. Bureau of Labor Statistics, Schedule of Selected Releases for November 2026; CNBC, Jobs report October 2026 (November 6, 2026); Reuters via Yahoo Finance, Fed seen sticking to December rate hike after jobs data (November 6, 2026); University of Michigan Surveys of Consumers, Preliminary Results for November 2026 (November 6, 2026); Reuters, US consumer sentiment improves in November (November 6, 2026); Freddie Mac, Mortgage Rates Decline for Third Consecutive Week to 7.18% (November 5, 2026); AAA, National Average Falls 12 Cents in One Week (November 5, 2026); J.D. Power and GlobalData, U.S. Automotive Forecast for October 2026 (October 22, 2026); NADA Market Beat (November 5, 2026); Hyundai Motor America, Record-Breaking October 2026 Sales (November 3, 2026); Kia America, Sixth Consecutive Month of Record-Breaking Sales (November 2026); RTTNews, Ford Motor U.S. sales for October, citing Ford data; Reuters via Charlotte Observer, Tesla to pull the plug on Cybertruck (November 6, 2026); Paul Tan, Tesla Cybertruck production to wind down in mid-2027 (November 6, 2026); Yahoo Autos, GM recalls Cadillac and Chevrolet EVs over brake software (November 8, 2026); NHTSA, $1.5 Million to Help States Alert Drivers About Vehicle Recalls (November 5, 2026); Federal Reserve Bank of New York, media advisory for the Q3 2026 Household Debt and Credit Report; U.S. Census Bureau, Retail Trade release schedule.